March 26, 2025

Where Did the Pension Go?

Where Did the Pension Go?

Where Did the Pension Go?

Why the truce that once existed between employers and workers unraveled.

There was a time when punching the clock meant you could purchase a home, provide for your family, and spend your golden years comfortably with a pension — a guaranteed, employer-funded retirement plan for the rest of your life.

That dream has long since vanished (and we don’t hear the phrase “golden years” anymore, either). In its place, workers across American industry have experienced wage stagnation, or seen their jobs outsourced. Meanwhile, the US economy only benefits a select few, and makes the struggle real for everyone else. One could blame any number of reasons for this notorious decline, but each argument stems from the same dynamic: a , when factories were pumping out more than the market could handle, and the private sector was no longer eager to pour money into new production.

Turning Back the Clock

At the end of World War II, American manufacturing kicked off a surge in productivity. This period of economic growth primarily advantaged white families, while much of Europe was still recovering from the financial and physical toll of the war. At the time, a kind of informal agreement emerged between corporations and workforces: So long as employees didn’t interfere in business operations, management would ensure steady wage increases.

This arrangement fostered a relatively depoliticized working class aligned with large labor unions. Still, it was worker-led organizing and direct action that helped secure gains like consistent raises and the  — achievements that improved the standard of living for working families nationwide and might not have materialized without such pressure.

Then, the So-Called Golden Age of Capitalism Came to a Close

By the 1970s, American businesses faced new international competition, driven largely by forces of globalization, as less industrialized nations advanced technologically. With profit margins thinning, the US government was  from the private sector. Essentially, whatever got in capital’s way had to go. That meant easing up on tariffs, lessening union power, and weakening labor laws.

Corporations started rolling back many of the hard-won gains achieved by workers on the factory floor. The system began to fracture, and the truce that once existed between employers and workers unraveled. The handshake deal embraced by boardrooms to maintain industrial stability started to fade away.

In this new era, American businesses maintained profit margins while the nation witnessed a significant decline in manufacturing. By the 1990s, large swaths of production jobs were outsourced abroad, and companies . The positions that stayed within the country were often restructured into smaller, non-unionized labor forces, mostly sprinkled throughout the Midwest and Southern regions.

Beneath these broader economic shifts was a structural challenge embedded in the pension itself. As medical innovations extended life expectancy, employers were on the hook for providing guaranteed income over longer and longer retirements. The cost of maintaining these plans surged; the investment risk sat squarely with the company. For many, the burden became unsustainable. So even beyond globalization and weakening unions, businesses had a practical reason to walk away.

Pensions Were Simply Too Expensive to Keep Alive

Workers could no longer rely on their employers to provide pensions. Instead, they were furnished with retirement-benefit packages that required them to become self-educated (and self-funded) in financial markets, and to increase their knowhow in order to navigate the promise of financial stability.

Enter: the defined contribution 401(k) plan.

Once  designed specifically as a tax shelter for C-suite executives, the 401(k) became popularized in the 1980s and 1990s as a new way for America’s middle class to find wealth on their own. It didn’t matter however many decades one may have spent in a specific trade. Whether sitting behind a desk or sweating on the factory floor, employees were now expected to contribute voluntarily from their paychecks, make complex investment decisions, and shoulder the full burden of securing a dignified retirement.

The 401(k) was rarely ever marketed as such a demanding product. Just keep contributing and don’t look at it was the widespread (albeit not ill-intentioned) mantra — as if it were so easy. Certainly millions of workers have succeeded in building abundant retirement funds through consistent and steadfast contributions, but for the majority of the workforce, the experience has been inadequate and cruel. A recent  found that in 2020, the median employee contribution to retirement accounts was less than $3,600, while the median account value hovered around $30,000.

Most wage-earning Americans are not equipped to handle the many demands that the 401(k) system places on them. “Most humans can’t arrange to save the right amount,”  economist Teresa Ghilarducci, who has studied the retirement crisis practically her entire working life, “invest the right way, avoid leakage, and distribute the money to last a lifetime.” The data speaks for itself: By 1970, approximately  had some form of guaranteed pension. Today, that figure has dropped  with access to such a plan. At the same time,  of the workforce actively contributes to 401(k)s.

There Was a Time When Being a Worker Also Meant Being an Owner

The responsibility for long-term financial security has shifted from employer to individual, forcing workers to fend for themselves in managing retirement planning. It wasn’t always this way, as older generations might recall a time when pensions were the norm. Those plans fostered a sense of ownership and loyalty to their employers; workers felt invested in the company’s success because the company, in return, was invested in their futures.

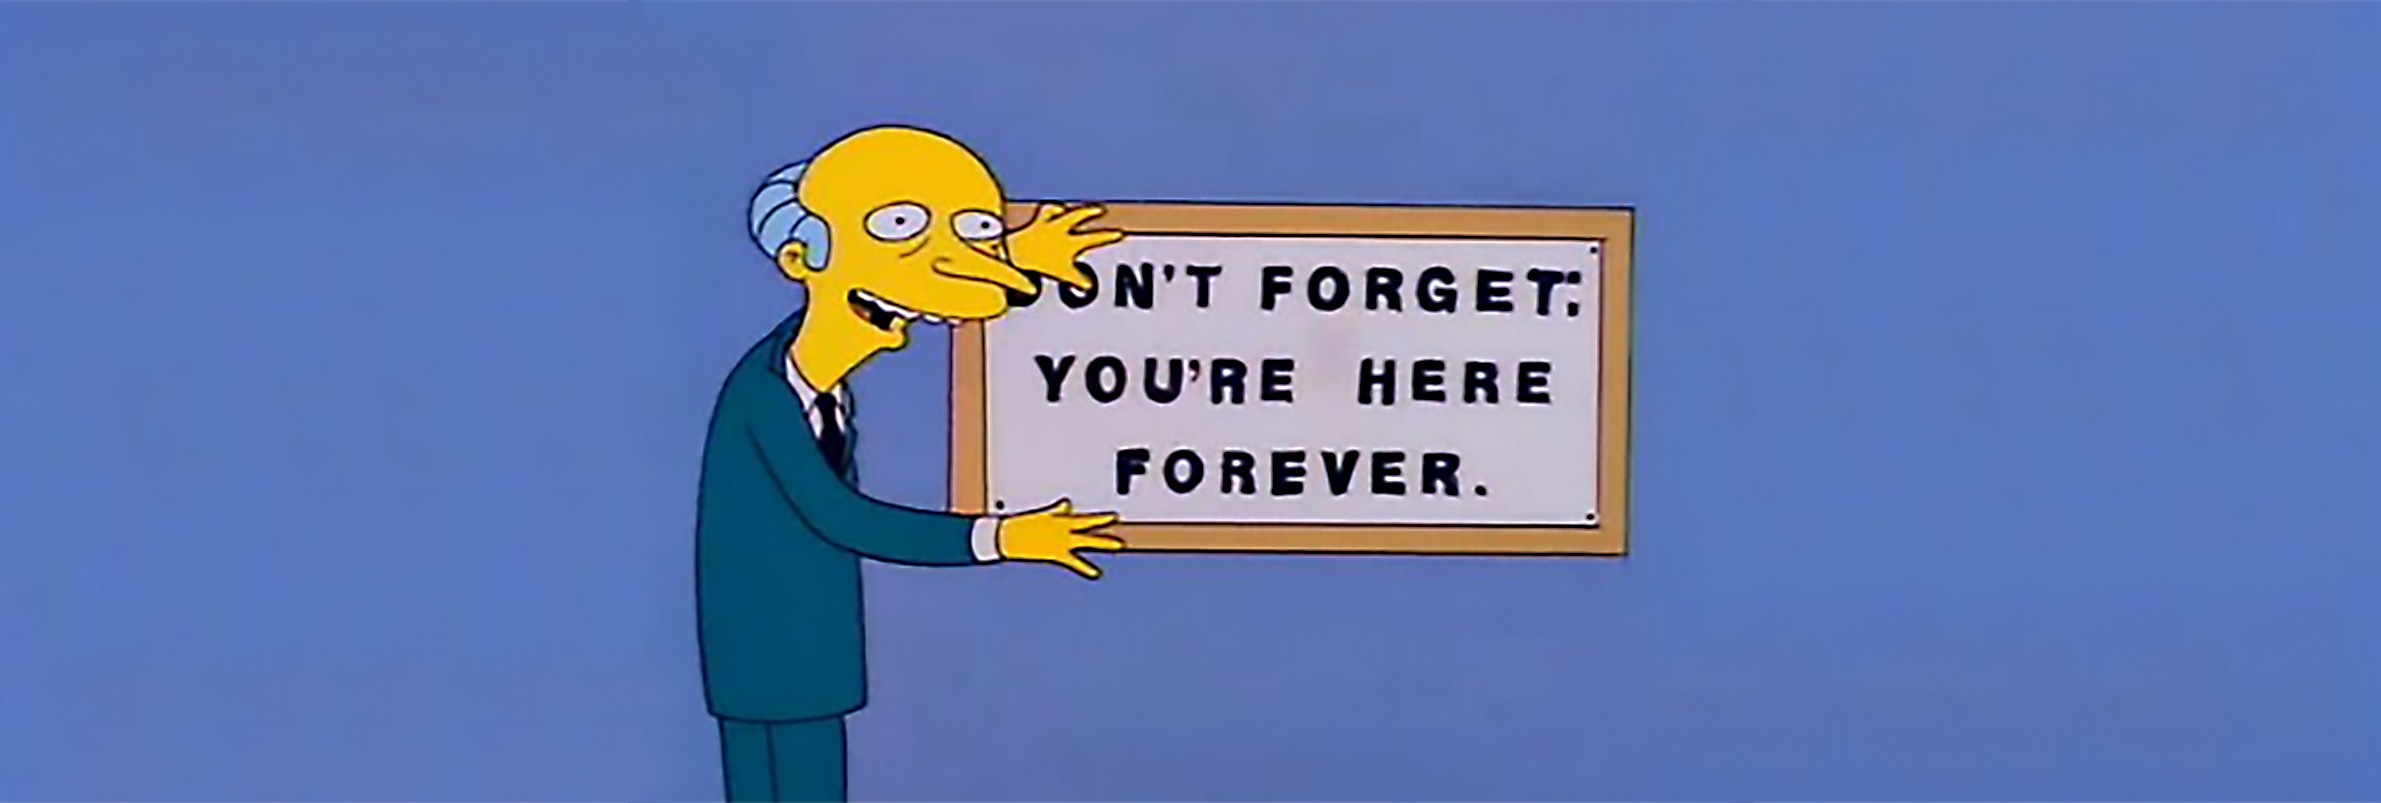
This sentiment is admittedly a little Disneyfied, but it was once very much a reality for working Americans. Today, the idea of spending decades with a single employer who also ensures your retirement is a virtual fantasy. Ironically, what was once considered a trap is now darkly romanticized. There’s a meme of The Simpsons’s Mr. Burns that occasionally makes the rounds in which Springfield’s local tyrant is posing next to a sign that reads, “Don't Forget. You're Here Forever” — a symbol of corporate servitude that, in today’s precarious labor market, feels like a joke many would happily trade flexibility for, if it meant that kind of certainty.
Now that retirement has been reduced to a solo project, what fills the gap once covered by pensions? Could technical innovations eventually help us navigate the challenge, or will Americans continue working longer and call it “freedom”? Either way, the distant concept of the golden years feels less like a destination than an improvisation.
This isn't your standard 401(k).

Meet the 401(k) that actually gets your team retirement ready.

This isn't your standard 401(k).

Meet the 401(k) that actually gets your team retirement ready.

This isn't your standard 401(k).

Meet the 401(k) that actually gets your team retirement ready.

© 2026 Basic Capital. All rights reserved.

Basic Capital Group Inc. and its affiliates and subsidiaries (collectively, "Basic Capital") provide this website and its contents for informational and educational purposes only. The information on this website is general in nature and is not intended to address the circumstances of any particular individual or entity.  Nothing on this website constitutes investment, financial, legal, tax, or accounting advice, nor should it be construed as a recommendation or endorsement of any specific investment product, strategy, or service. Basic Capital does not provide legal, tax, or accounting advice. You should consult with your own qualified financial, legal, and tax advisors before making any investment decisions. Our site uses a third party service to match browser cookies to your contact information. We then use another company to send special offers on our behalf.

Recordkeeping Services

Recordkeeping services are provided through Basic Capital Recordkeeping Services LLC, a wholly owned subsidiary of Basic Capital Group, Inc. Unless expressly agreed to in writing, Basic Capital Recordkeeping Services LLC does not act as a fiduciary under the Employee Retirement Income Security Act of 1974, as amended, with respect to any employee benefit plan.

Investment Advisory Services

Investment advisory services are provided through Basic Capital Advisors LLC, a wholly owned subsidiary of Basic Capital Group Inc. registered with the State of New York as an investment adviser. Registration does not imply a certain level of skill or training. Investing involves risk, including the potential loss of principal. Past performance is not indicative of future results.
Investments in securities are: Not FDIC Insured • Not Bank Guaranteed • May Lose Value.
Neither Basic Capital Advisors LLC nor its affiliates are a registered broker-dealer or engage in securities brokerage activities. Furthermore, Basic Capital Advisors LLC and its affiliates do not act as a broker-dealer.

Investment Financing (“The Retirement Mortgage”)

Basic Capital’s investment financing arrangement called The Retirement Mortgage is not a security registered under the Securities Act of 1933 or an investment company registered under the Investment Company Act of 1940. This arrangement is not subject to the same regulatory requirements as the investment advisory services provided by Basic Capital Advisors LLC. The investment financing arrangement involves the use of financing or leverage, which carries additional and significant risks beyond those associated with standard investing. This arrangement may not be suitable for all investors. You should carefully consider the investment objectives, risks, terms and conditions, fees and expenses of The Retirement Mortgage before taking advantage of The Retirement Mortgage.  Please review all applicable terms, conditions, and risk disclosures specific to the investment financing arrangement before proceeding.

Basic Capital, 52 Walker Street, 5th Floor, New York, NY 10013 | 888-460-4901

© 2026 Basic Capital. All rights reserved.

Basic Capital Group Inc. and its affiliates and subsidiaries (collectively, "Basic Capital") provide this website and its contents for informational and educational purposes only. The information on this website is general in nature and is not intended to address the circumstances of any particular individual or entity.  Nothing on this website constitutes investment, financial, legal, tax, or accounting advice, nor should it be construed as a recommendation or endorsement of any specific investment product, strategy, or service. Basic Capital does not provide legal, tax, or accounting advice. You should consult with your own qualified financial, legal, and tax advisors before making any investment decisions. Our site uses a third party service to match browser cookies to your contact information. We then use another company to send special offers on our behalf.

Recordkeeping Services

Recordkeeping services are provided through Basic Capital Recordkeeping Services LLC, a wholly owned subsidiary of Basic Capital Group, Inc. Unless expressly agreed to in writing, Basic Capital Recordkeeping Services LLC does not act as a fiduciary under the Employee Retirement Income Security Act of 1974, as amended, with respect to any employee benefit plan.

Investment Advisory Services

Investment advisory services are provided through Basic Capital Advisors LLC, a wholly owned subsidiary of Basic Capital Group Inc. registered with the State of New York as an investment adviser. Registration does not imply a certain level of skill or training. Investing involves risk, including the potential loss of principal. Past performance is not indicative of future results.
Investments in securities are: Not FDIC Insured • Not Bank Guaranteed • May Lose Value.
Neither Basic Capital Advisors LLC nor its affiliates are a registered broker-dealer or engage in securities brokerage activities. Furthermore, Basic Capital Advisors LLC and its affiliates do not act as a broker-dealer.

Investment Financing (“The Retirement Mortgage”)

Basic Capital’s investment financing arrangement called The Retirement Mortgage is not a security registered under the Securities Act of 1933 or an investment company registered under the Investment Company Act of 1940. This arrangement is not subject to the same regulatory requirements as the investment advisory services provided by Basic Capital Advisors LLC. The investment financing arrangement involves the use of financing or leverage, which carries additional and significant risks beyond those associated with standard investing. This arrangement may not be suitable for all investors. You should carefully consider the investment objectives, risks, terms and conditions, fees and expenses of The Retirement Mortgage before taking advantage of The Retirement Mortgage.  Please review all applicable terms, conditions, and risk disclosures specific to the investment financing arrangement before proceeding.

Basic Capital, 52 Walker Street, 5th Floor, New York, NY 10013 | 888-460-4901

© 2026 Basic Capital. All rights reserved.

Basic Capital Group Inc. and its affiliates and subsidiaries (collectively, "Basic Capital") provide this website and its contents for informational and educational purposes only. The information on this website is general in nature and is not intended to address the circumstances of any particular individual or entity.  Nothing on this website constitutes investment, financial, legal, tax, or accounting advice, nor should it be construed as a recommendation or endorsement of any specific investment product, strategy, or service. Basic Capital does not provide legal, tax, or accounting advice. You should consult with your own qualified financial, legal, and tax advisors before making any investment decisions. Our site uses a third party service to match browser cookies to your contact information. We then use another company to send special offers on our behalf.

Recordkeeping Services

Recordkeeping services are provided through Basic Capital Recordkeeping Services LLC, a wholly owned subsidiary of Basic Capital Group, Inc. Unless expressly agreed to in writing, Basic Capital Recordkeeping Services LLC does not act as a fiduciary under the Employee Retirement Income Security Act of 1974, as amended, with respect to any employee benefit plan.

Investment Advisory Services

Investment advisory services are provided through Basic Capital Advisors LLC, a wholly owned subsidiary of Basic Capital Group Inc. registered with the State of New York as an investment adviser. Registration does not imply a certain level of skill or training. Investing involves risk, including the potential loss of principal. Past performance is not indicative of future results.
Investments in securities are: Not FDIC Insured • Not Bank Guaranteed • May Lose Value.
Neither Basic Capital Advisors LLC nor its affiliates are a registered broker-dealer or engage in securities brokerage activities. Furthermore, Basic Capital Advisors LLC and its affiliates do not act as a broker-dealer.

Investment Financing (“The Retirement Mortgage”)

Basic Capital’s investment financing arrangement called The Retirement Mortgage is not a security registered under the Securities Act of 1933 or an investment company registered under the Investment Company Act of 1940. This arrangement is not subject to the same regulatory requirements as the investment advisory services provided by Basic Capital Advisors LLC. The investment financing arrangement involves the use of financing or leverage, which carries additional and significant risks beyond those associated with standard investing. This arrangement may not be suitable for all investors. You should carefully consider the investment objectives, risks, terms and conditions, fees and expenses of The Retirement Mortgage before taking advantage of The Retirement Mortgage.  Please review all applicable terms, conditions, and risk disclosures specific to the investment financing arrangement before proceeding.

Basic Capital, 52 Walker Street, 5th Floor, New York, NY 10013 | 888-460-4901